
Strong but concentrated economic growth
Raymond James Chief Economist Eugenio J. Alemán discusses current economic conditions.
The strength of the US economy during the third quarter was hardly a surprise. We expected economic growth of 3.5%, and the first estimate came in only slightly below that at a 3.4% quarter-over-quarter, seasonally adjusted annualized rate. Consumer spending and investment tied to the AI and data center buildout remained the primary drivers of growth. However, the conflict with Iran also had a larger-than-expected impact on economic activity. Federal defense spending increased 11.7% during the quarter while nondefense spending surged 22.2%. As a result, government consumption and investment rose 5.3% after edging down 0.1% in the second quarter.
As we have argued repeatedly in previous reports, consumer demand remains the backbone of the US economy. Not only does it account for roughly 70% of GDP, but it is also the most stable component of economic activity. The investment component, however, is a different story. Although smaller than consumption, it is significantly more volatile and often plays a central role in economic downturns. When investors turn cautious, what John Maynard Keynes called "animal spirits" can weaken, leading to slower investment and, ultimately, slower economic growth.
This is where our concern lies.
Financial markets often assume that today's growth trends will continue indefinitely. Former Federal Reserve Chairman Alan Greenspan famously described this tendency as irrational exuberance. We are not suggesting that current conditions resemble the periods Greenspan had in mind. Nevertheless, the remarkable performance of the stock market, combined with the outsized contribution of AI- and data center-related spending to overall investment and GDP growth, deserves attention.
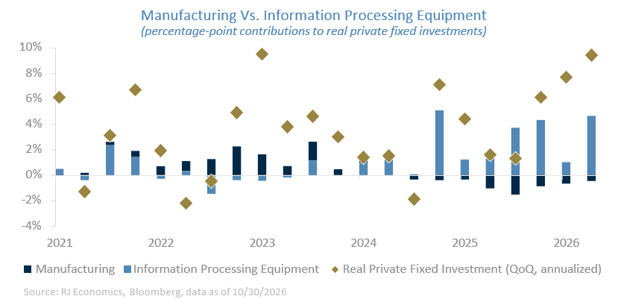
As the graph above shows, information processing equipment has made an extraordinary contribution to real private fixed investment growth since early 2025. In the third quarter alone, it accounted for slightly more than half of total real private fixed investment growth.
We are not arguing that this trend cannot continue for several more years. However, it raises the possibility that investment growth is becoming increasingly dependent on a single segment of the economy while other sectors lag behind. At the same time, a sizable share of this investment is imported. This helps explain the widening US trade deficit and the strength in capital goods imports. During the third quarter, net exports reduced real GDP growth by 3.32 percentage points, while gross private domestic investment added 3.27 percentage points.
That does not mean the contribution from investment was entirely offset by imports. Capital goods represent only part of total imports, which also include consumer goods, industrial supplies and other products. Furthermore, domestic production of computer and electronic products has been growing at an exceptionally strong pace, indicating that US manufacturers are also benefiting from the AI and data center buildout.
The next chart presents our estimate of the contribution of AI- and technology-related investment to real GDP growth. The figures through 2Q26 are shown in the vertical bars. It is important to note that these estimates represent gross contributions and do not detract the imported portion of that investment.
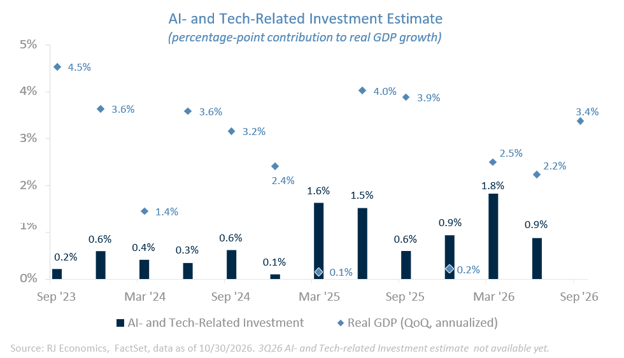
Importantly, the heavy reliance on imported capital goods is not necessarily a negative development. While it reduces the immediate boost from investment to domestic GDP growth, it supports the creation of productive capacity that can enhance future economic output. In other words, the economy is investing in its future, even if some of the equipment is sourced abroad.
Bottom line
The AI investment boom is delivering real economic gains and supporting market performance, but growth has become increasingly concentrated. As long as AI-related spending continues to expand, both the economy and markets should remain well supported. The bigger risk is not weak growth today, but whether expectations have moved too far ahead of the eventual payoff.
Economic and market conditions are subject to change.
Opinions are those of Investment Strategy and not necessarily those of Raymond James and are subject to change without notice. The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. There is no assurance any of the trends mentioned will continue or forecasts will occur. Past performance may not be indicative of future results.